Learning how to finance a golf cart the smart way can save you real money and a lot of stress, whether you want a brand-new lithium cruiser for the neighborhood or a dependable used gas cart for the campground. The right plan keeps your monthly payment comfortable, protects your credit, and gets you driving sooner.
At Custom Carts in Northeast Ohio, we help buyers compare dealer financing, credit union loans, personal loans and cash every week. This guide explains how to finance a golf cart step by step. It walks you through each option, explains what lenders look at, and shows you how to build a budget that fits your life, not just the sticker price.
Why It Pays to Understand How to Finance a Golf Cart
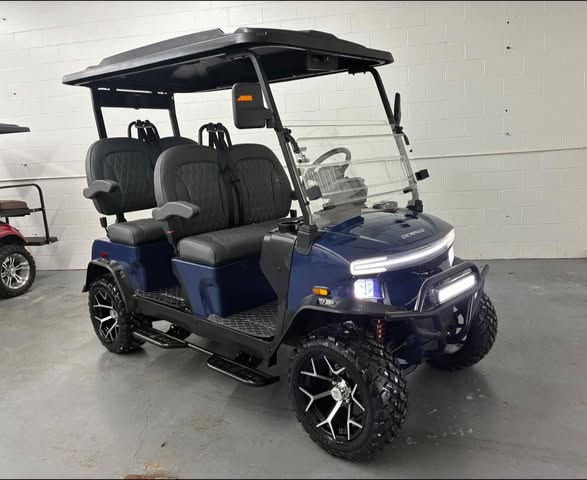
A modern golf cart is a real vehicle purchase. Across our recent listings, well-kept used electric carts can start in the low thousands, late-model gas carts often land in the $5,000 to $9,000 range, and new lithium carts with lift kits, touchscreens and street-legal equipment commonly run from about $8,000 to $14,000. That is a meaningful number for most households, which is exactly why knowing how to finance a golf cart matters.
Knowing how to finance a golf cart gives you choices. Instead of settling for a smaller, older cart than you really want, or draining your emergency savings, you can spread the cost over time at a payment you control. The key is choosing the right lender, the right term and the right down payment.
Cash vs. Financing: A Quick Reality Check
Paying cash is simple and avoids interest entirely. But many buyers prefer to keep their savings liquid, especially when a promotional offer makes borrowing inexpensive. Neither choice is wrong. Whatever you decide about how to finance a golf cart, compare the total cost of each path before you sign anything.
- Cash – no loan to repay, no credit check, fastest paperwork.
- Dealer financing – convenient, often has promotional offers, approval handled at the dealership.
- Credit union or bank loan – competitive rates for members with solid credit.
- Personal loan – flexible and unsecured, but rates can be higher.
Your Main Options: How to Finance a Golf Cart in Ohio
Most buyers in Ohio choose between four paths. Each has strengths, and the best fit depends on your credit, your timeline and how much paperwork you want to handle. Here is how to finance a golf cart through each channel, along with what to watch for.
1. Dealer Financing Through Third-Party Lenders
Dealer financing is the most popular answer to how to finance a golf cart because it happens in one place. At Custom Carts, financing is available with approved credit through our lending partners, which are established third-party lenders that specialize in powersports and recreational vehicles. You pick the cart, fill out one application, and the lender decides on approval, rate and term.
Because these lenders focus on vehicles like golf carts, ATVs and UTVs, they understand the collateral and can often approve quickly. For many families, this is the easiest answer to how to finance a golf cart without extra trips to the bank. Visit our golf cart financing page to see how the application works and what you will need.
2. Manufacturer and Lender Promotions
Across the industry, manufacturers and lenders sometimes run promotions on select new carts, such as a reduced or 0% APR for a limited period or low-down-payment programs. This is a general description of the market, not a current offer. If you are researching how to finance a golf cart at the lowest possible cost, these offers can be excellent value, but terms vary. Promotions typically require strong credit, apply only to specific models, and may have shorter terms or deadlines.
Always read the fine print. Ask whether the promotional rate lasts for the full term or is a deferred-interest plan, where interest can be charged back if the balance is not paid in full by a certain date. At Custom Carts, any promotional financing is with approved credit through our lending partners, and offers change, so ask what is available on the specific cart you want when you call.
3. Credit Union and Bank Loans
If you already belong to a credit union, add it to your list when you compare how to finance a golf cart. Check its recreational vehicle or personal loan rates. Credit unions often offer competitive rates to members with good credit. Some treat a golf cart like a recreational vehicle loan, while others use an unsecured personal loan product.
The advantage is that you shop with pre-approval in hand, which makes you a cash buyer at the dealership. The trade-off is extra paperwork and time, and some lenders will not finance older or used carts, or they may require a minimum loan amount.
4. Personal Loans
Online and bank personal loans are unsecured, so the cart is not collateral. That flexibility is useful if you are buying a used cart from a private seller or want to bundle accessories. However, unsecured loans usually carry higher rates than secured vehicle loans, especially for fair or rebuilding credit. It is a less common but sometimes useful answer to how to finance a golf cart when the seller is not a dealer.
How to Finance a Golf Cart: Options Compared
The table below summarizes how to finance a golf cart through each path, with the typical strengths and trade-offs of each path. Actual rates and terms depend on your credit profile and the lender, so treat this as a general guide rather than a quote.
| Option | Best For | Typical Pros | Typical Cons |
|---|---|---|---|
| Dealer financing (third-party lenders) | One-stop convenience | Fast decisions, promotions on select carts, handled at purchase | Rates vary by credit; promos limited to qualifying buyers |
| Manufacturer or lender promotions | Strong credit, new carts | Lower borrowing cost, smaller upfront cost | Model restrictions, deadlines, possible deferred interest |
| Credit union or bank loan | Members with good credit | Competitive rates, pre-approval power | More paperwork, may limit used or older carts |
| Personal loan | Private-party or flexible purchases | No collateral, quick online funding | Often higher rates than secured loans |
| Cash | Buyers with ample savings | No borrowing cost, simplest deal | Reduces emergency funds |
What Lenders Look at Before They Approve You
Understanding the approval process is a big part of learning how to finance a golf cart with confidence. Lenders are trying to answer one question: how likely are you to repay on time? They use several factors to decide.
- Credit score and history – on-time payments, how long you have had credit, and any recent collections or late payments.
- Debt-to-income ratio – how much of your monthly income already goes to car loans, mortgages, cards and other debts.
- Income and employment stability – steady, verifiable income makes approval easier.
- Down payment – more money down lowers the lender’s risk and can improve your terms.
- The cart itself – new versus used, age, price and brand can affect what a lender will offer.
Tips to Strengthen Your Application
Before you decide how to finance a golf cart, check your credit reports and dispute any errors you find. Pay down revolving balances if you can, because lower card utilization often helps your score. Avoid opening new credit accounts in the weeks before you shop, and gather recent pay stubs or tax returns if you are self-employed.
If your credit is still rebuilding, a larger down payment, a co-applicant or a lower-priced cart can make approval more realistic.
How Much Should You Put Down?
There is no single rule, but a meaningful down payment almost always improves the deal, which makes it one of the biggest levers in how to finance a golf cart affordably. Many buyers aim to put a meaningful share of the purchase price down, though some lender promotions on select new models require less up front, always with approved credit.
A larger down payment helps in three ways. It lowers your monthly payment, reduces the total interest you pay over the life of the loan, and keeps you from owing more than the cart is worth in the first year or two. That last point matters if you think you might sell or trade up down the road.
Using Your Trade-In as a Down Payment
Trade-in equity is one of the most overlooked tools when people research how to finance a golf cart. If you already own a cart, its value can go straight toward your new purchase, reducing the amount you need to borrow. At Custom Carts, trade-ins are welcome, and we take everything from older gas carts to late-model lithium units.
To get the strongest trade value, clean the cart, gather service records, charge the batteries fully and note any upgrades. Start with our trade-in page to tell us about your current cart.

Building a Budget That Actually Works
The monthly payment is only part of what you will spend. A realistic budget is the most practical piece of learning how to finance a golf cart, because it prevents surprises after you bring the cart home. Think in terms of total cost of ownership, not just the loan.
Costs to Include Beyond the Payment
- Insurance – many homeowners policies limit or exclude golf cart coverage, especially off your property. A standalone cart policy is often affordable.
- Registration and titling – if you plan to make the cart street legal, budget for Ohio BMV fees and any required inspection.
- Maintenance – tires, brakes, battery care for electric carts, and oil, filters and belts for gas carts.
- Charging or fuel – electricity for electric carts is usually modest; gas carts need fuel and occasional tune-ups.
- Accessories – enclosures for Ohio weather, lights, seat covers, storage and sound systems add up.
- Storage – garage space or winter storage if you do not have room at home.
A Simple Budgeting Rule of Thumb
Add your estimated payment, insurance and a monthly maintenance reserve together. If that total still feels comfortable after your other bills and savings goals, you are in a good position. This quick test is the heart of how to finance a golf cart responsibly. If it feels tight, consider a longer term, a bigger down payment, or a slightly less expensive cart.
Remember that a longer term lowers the payment but usually increases the total interest you pay. Available loan terms for recreational vehicles vary by lender, by the cart and by your credit, so compare a shorter and a longer option before you choose.
New vs. Used: How Financing Differs
The age of the cart changes how to finance a golf cart in a few practical ways. New carts are the most likely to qualify for promotional rates and the longest terms, and many come with manufacturer warranties. For example, Denago listings we carry include a 2-year cart warranty and an 8-year battery warranty, which can make a new cart easier to budget for.
Used carts are often cheaper to buy, but some lenders apply age limits, shorter terms or slightly higher rates. A newer used cart with a good service history is usually the easiest used option to finance. If you are shopping pre-owned, read our used golf cart checklist before you commit.
| Factor | New Cart | Used Cart |
|---|---|---|
| Promotional rates | Most likely, with approved credit | Less common |
| Loan term | Often longer terms available | May be shorter depending on age |
| Warranty | Manufacturer coverage on many models | Limited or none, depending on seller |
| Purchase price | Higher | Lower |
| Best fit | Buyers who want the latest features and lithium power | Budget-focused buyers with a trusted inspection |
Step-by-Step: How to Finance a Golf Cart at Custom Carts
If you want the simplest route, here is how to finance a golf cart with us from first look to first drive. Most of the process can start by phone or text, and we will walk you through every step.
- Browse the inventory. Shop our new golf carts, used golf carts and lithium golf carts to narrow down the models you like.
- Set your budget. Decide on a comfortable monthly payment and a down payment amount.
- Ask about current offers. Call or text to learn which carts have promotions available with approved credit.
- Apply. Complete the credit application with our lending partners. Decisions are often fast.
- Review the terms. Look at the APR, term length, total cost and any promotional conditions.
- Add your trade-in. Apply your trade value toward the down payment if you have one.
- Take delivery. Pick up your cart or ask about local delivery. Wider delivery is quoted on request.

Common Mistakes to Avoid
Even careful buyers can trip up. Avoiding these common mistakes is just as important as knowing how to finance a golf cart in the first place.
Focusing Only on the Monthly Payment
A low payment can hide a long term and a high total cost. Always ask for the total amount you will pay over the life of the loan and compare offers on that basis, not just the monthly number. Smart shoppers who study how to finance a golf cart always look at the full cost.
Skipping the Fine Print on Promotions
Promotional financing offers are great when you understand them. Confirm whether interest is waived or deferred, what happens if you miss a payment, and whether the promotion ends before your loan does.
Forgetting About Insurance and Registration
Buyers learning how to finance a golf cart for road use sometimes forget the extra steps. If a street-legal cart is your goal, our guide to street-legal golf carts in Ohio explains the basics, and the Ohio Bureau of Motor Vehicles is the official source for registration and titling rules.
Buying More Cart Than You Need
Lift kits, touchscreens and six seats are fun, but they add cost. Be honest about how you will use the cart. Our guide to choosing a 4 vs 6 passenger golf cart can help you right-size your purchase.
Choosing the Right Cart for Your Financing Plan
Your power source changes how to finance a golf cart sensibly, because it affects both the price and long-term costs. Lithium carts usually cost more up front but need far less routine battery care, while traditional 48V lead-acid carts are cheaper to buy but require regular watering and eventual battery replacement. Gas carts offer long range and quick refueling but need engine maintenance.
If you are torn between power types, our comparison of gas vs electric golf carts and our guide to lithium golf cart batteries lay out the trade-offs. Factoring these costs in is a smart part of how to finance a golf cart without regrets.
Think About Resale Value
Resale value is an underrated part of how to finance a golf cart wisely. Well-known brands and well-maintained carts tend to hold value better. That matters if you plan to trade up in a few years, because strong resale value becomes trade-in equity for your next cart. Keep service records and follow a regular golf cart maintenance routine to protect that value.

Frequently Asked Questions
What credit score do I need to finance a golf cart?
When you research how to finance a golf cart, you will find there is no single minimum, because each lender sets its own criteria. Stronger credit generally qualifies for the best rates and promotional offers, while buyers with fair or rebuilding credit may still be approved with a larger down payment or a co-applicant. Financing at Custom Carts is always with approved credit through our lending partners.
Can I get promotional financing on a golf cart?
Sometimes. Select new carts may qualify for manufacturer or lender promotions, but terms vary by lender, model and credit profile. Promotions usually require approved credit and may have deadlines. Ask about current offers when you contact us.
Is it better to finance through a dealer or a credit union?
It depends on your situation. Dealer financing is convenient and may include promotions, while a credit union may offer a competitive rate if you are a member with good credit. When deciding how to finance a golf cart, it is smart to compare both and choose the lowest total cost.
Can I finance a used golf cart?
Yes, in many cases. Learning how to finance a golf cart that is pre-owned works much the same way as a new one, with a few differences. Some lenders apply age limits or shorter terms to used carts, so newer pre-owned carts are typically the easiest to finance. A personal loan is another option for older carts or private-party sales.
What documents do I need to finance a golf cart?
Most lenders ask for a valid driver’s license, proof of income such as recent pay stubs or tax returns, and your contact and residence details. Having these ready is a simple way to make how to finance a golf cart a faster, smoother process.
Can I use my current golf cart as a down payment?
Yes. Trade-ins are welcome at Custom Carts, and your trade value can be applied toward your down payment, reducing how much you borrow and lowering your monthly payment.
Ready to Finance Your Next Golf Cart?
Now you know how to finance a golf cart with confidence: compare your options, understand what lenders look for, make a solid down payment, use your trade-in equity, and budget for the full cost of ownership. With a clear plan, getting the cart you want is easier than you might think.
When you are ready, shop our full inventory of new and used gas, electric and lithium golf carts. Have questions about how to finance a golf cart, current offers, or starting an application? Contact us online or call or text (330) 752-8570 to schedule a visit with our team in Northeast Ohio. Financing is available with approved credit.